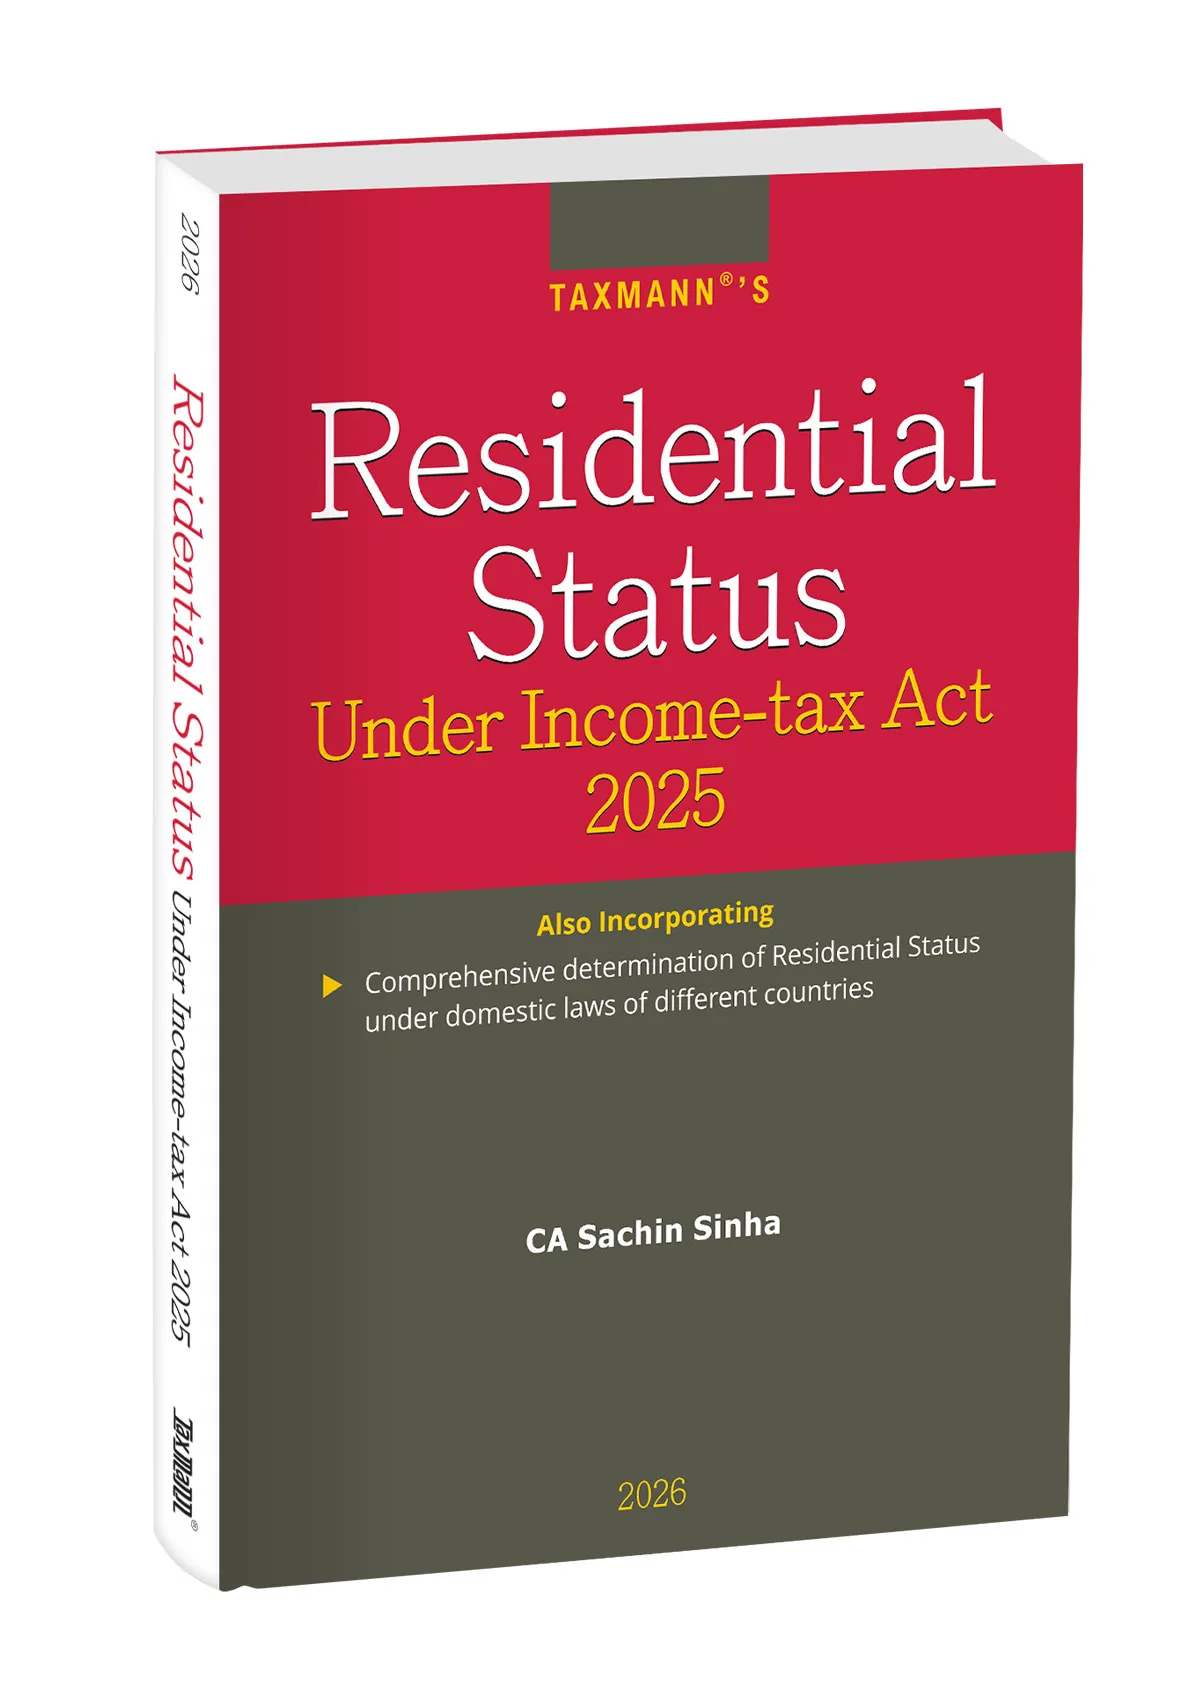
Residential Status under Income-tax Act 2025 By Sachin Sinha
Original price was: ₹645.00.₹416.00Current price is: ₹416.00.
Residential Status under Income-tax Act 2025 is a single-subject treatise. It is written for the practitioner who must reach a defensible conclusion on a residence question and produce the work to support it.
The book is written on the Income-tax Act 2025, and is among the first titles to restate residence law under the new enactment. It is designed to be used while both statutes are still in play: more than fifty bracketed in-line cross-references tie each provision to its counterpart under the Income-tax Act 1961, running in both directions, and a dedicated chapter of nineteen FAQs deals with nothing but the repeal, the savings clause and the questions that arise when a taxpayer’s history straddles the two Acts.
Three things separate it from a conventional commentary. First, it argues rather than merely reports: where the authorities conflict, or the statute is silent, the author sets out the competing readings and reasons for a stated position, and where he cannot settle a point he says so and identifies the difficulty. Second, it does not stop at the Indian border, devoting a full chapter to the domestic residence rules of eleven other jurisdictions so that a dual-residence question can be tested from both ends. Third, it reproduces its primary material rather than summarising it: the OECD Commentary on Article 4 with the member States’ Observations and Reservations, the UN Model Commentary, the CBDT Guiding Principles on POEM in full, and seven circulars and releases in an appendix.
The practical apparatus is substantial. Fifteen worked case studies on dated fact patterns close the book, day-count and income-analysis tables carry the arithmetic in full, roughly two dozen short worked examples are threaded through the commentary, and every decision cited is footnoted at the foot of its own page and indexed by paragraph number in a 63-entry List of Cases.
This book is intended for the following audience:
- Chartered Accountants and Tax Practitioners advising internationally mobile individuals, expatriates, seafarers, NRIs, PIOs and returning Indians
- International Tax and Transfer Pricing Specialists handling treaty entitlement, tie-breaker analysis, POEM exposure and treaty-shopping challenges
- Corporate Tax Teams and In-house Counseloff Multinational Groups with foreign subsidiaries, holding structures, offshore management arrangements or re-domiciliation plans
- Advocates and Litigators appearing in residency, treaty-benefit, TRC and GAAR disputes before the Tribunal, the High Courts and the Supreme Court
- Officers of the Tax Administration assessing residence claims, TRC-supported treaty positions, deemed residency cases and POEM determinations
- Trustees, Fiduciaries and Private Client Advisers determining the status of specific and discretionary trusts
- Payers and Withholding-tax Teams who must classify a payee before deducting under the resident or non-resident table of section 393
- NRIs, HNIs and Globally Mobile Professionals with income streams and homes in more than one country
- Academicians, Faculty and Advanced Students of international taxation, including candidates for the CA Final and the ICAI Diploma in International Taxation
The Present Publication is the 1st Edition, updated till August 2026. It is authored by CA. Sachin Sinha, with the following noteworthy features:
- [A Whole Book On One Concept] The subject that a general commentary disposes of in a few pages is given 161 pages here, with the analysis pushed down to the level of individual statutory phrases: ‘place’, ‘key management’, ‘in substance made’, ‘affairs’, ‘situated wholly’, ‘set up’, ‘day’, ‘year’, ‘leaves India’
- [Dual-Act Usability] More than fifty bracketed in-line mappings connect the 2025 provisions to their 1961 counterparts, and back again, so a reader carrying forward an old position can follow it across the change without a separate concordance
- [A Transition Chapter, Not A Transition Paragraph] Nineteen FAQs are devoted to the repeal and savings problem, including which Act governs a reassessment initiated after 1st April 2026, how the continuity counts reach back into repealed-Act years, and what happens to positions already taken under the NRI concessional regime
- [The Author Takes Positions] On the foreign LLP, on the availability of the treaty tie-breaker to a deemed resident, on whether a profession once set up can be set up again, and on the treatment of the arrival date in a day-count, the book reasons to a conclusion instead of listing authorities. Where an answer is genuinely unavailable, it leaves the question open rather than papering it over
- [Comparative by Design] A full chapter covers the residence rules of Singapore, Mauritius, the UAE, the UK, the USA, Australia, China, France, Germany, Hong Kong and the Netherlands, each for individuals and for companies, with the divergence from Indian law stated at each point
- [Primary Material Reproduced, Not Paraphrased] The OECD Commentary on Article 4 runs verbatim with its own paragraph numbering, followed by the Observations of three States and the Reservations of nine, then the UN Model Commentary including the Committee of Experts’ recorded minority view. The CBDT Guiding Principles on POEM are reproduced in full with their five illustrations
- [Updated to the Newest Authority] The book is up to date as of August 2026 and aligns with the 2026 rules and forms, including Rule 8, Rule 75, Rule 76, and Forms 41 and 42
- [Built To Be Worked From] Fifteen case studies, dated fact patterns, day-count tables, computation tables with a Remarks column, and roughly two dozen inline worked examples give the reader arithmetic to follow rather than propositions to accept
- [Navigable] Every cross-reference in the book, including the 63-entry List of Cases, points to a paragraph number rather than a page, and the running heads carry that paragraph number on every page
The coverage of the book is as follows:
- Chapter 1 — Introduction
- Opens the book by inventorying the provisions across the Act whose operation turns on residential status: the charging and scope provisions, resident-only benefits under the Schedules, provisions confined to non-residents, Chapter XIII-E, transfer pricing, agency and withholding. Also introduces the themes the later chapters develop, and covers the evidentiary problem of open borders and FRRO records, and the foreign tax credit question
- Chapter 2 — Significance of the Residency Test
- Takes the scope-of-total-income provisions apart and works through the terms they turn on: ‘residence’, ‘business controlled in India’ against ‘business controlled from India’, ‘set up’, and ‘ordinarily resident’. Includes the treatment of part-year residence and a comparison with the US dual-status alien
- Chapter 3 — Meaning of Resident and Non-resident
- Covers the statutory definitions, the meaning of ‘India’ and its exclusion of Indian ships beyond territorial waters, the separateness of the two individual tests, the tie-breaker questionnaire and its evidentiary weight, split residency, dual residency, and fiscally transparent entities under the MLI
- Chapter 4 — Residential Status for Individuals
- The most computation-heavy chapter and the one with the most sub-paragraphs. Covers the 182-day and alternative tests; the treatment of arrival and departure dates, with a single travel schedule tabulated twice to show the total moving from 179 to 186 days and so across the threshold; the meaning of ‘day’ and ‘year’; ‘leaves India for the purposes of employment’; visa category; crew members of Indian and foreign-bound ships under Rule 8; evidence of days and lost or impounded passports; the visiting-NRI relaxation; and a fully worked computation of the fifteen-lakh threshold
- Chapter 5 — Residential Status of HUF, Firm and AOP
- The shortest doctrinal chapter. Covers the control-and-management test and the phrases it rests on, whether a firm is a separate legal entity, and the author’s conclusion that a foreign LLP is a company and so falls to be tested under POEM
- Chapter 6 — Deemed Resident or Stateless Person
- Covers citizenship, domicile, the catch-all criterion and ‘liable to tax’; whether a deemed resident can claim treaty benefit, foreign tax credit or a TRC; the withholding problem for the payer, with a suggested safeguard; and the return-filing obligation
- Chapter 7 — Ordinary Resident and Not Ordinary Resident in India
- Works through the three RNOR limbs with worked examples for a first-time arrival and a long-term visiting citizen, covers the benefits of RNOR status, the application of the test to an HUF through its manager, the change-of-karta difficulty, and why the category has no treaty counterpart
- Chapter 8 — Residential Status of a Company
- The second-longest chapter. Separates the foreign company from the non-resident company, covers the practical difficulties POEM creates for a company never previously assessed in India, and breaks the POEM definition into its five constituent phrases, each with its own sub-paragraph. Includes the 2017 OECD revision and the MLI treatment of dual-resident entities, and reproduces CBDT Circular No. 6 of 2017 in full, with the active-business test, the two-stage process, the guiding factors, the secondary factors, the collegium safeguard and five worked illustrations
- Chapter 9 — Interplay of GAAR with Residency Test
- The shortest chapter. Sets out four modes of treaty abuse, the centre-of-vital-interests analysis, the anti-treaty-shopping language now in the Act and its identity with the MLI preamble, and treaty override
- Chapter 10 — Residential Status of the Trust
- Builds the trust-law groundwork from the Indian Trusts Act 1882 before reaching the tax question, works through the conflicting authorities on whether a trust is an individual, an AOP, a BOI or an artificial juridical person, and then settles the residence of specific and discretionary trusts, including the mixed-beneficiary case. Carries both of the book’s diagrams
- Chapter 11 — Tax Residency Certificate
- Traces the certificate from the Budget Memorandum of 2012 through Azadi Bachao Andolan and Circular No. 789 to Blackstone Capital Partners and then Tiger Global, and closes on Rule 75 of the Income-tax Rules, 2026 and what it changes for Form 41
- Chapter 12 — Interplay of Domestic Provisions of Residential Status vis-a-vis Treaty Provisions
- The longest chapter in the book. Covers the tie-breaker ladder for individuals and the separate rule for other persons, analyses the object and purpose of Article 4 under six heads, and then reproduces the OECD Commentary paragraph by paragraph with its own numbering, the Observations of Chile, Spain and Hungary, the Reservations of Japan, Korea, France, the United States, Portugal, Sweden, Israel, Estonia and Latvia, and the UN Model Commentary with the alternative pre-2017 paragraph 3
- Chapter 13 — Residential Status in Different Contracting States
- The comparative chapter. One block per jurisdiction, each with a snapshot table and separate treatment of individuals and companies: Singapore, Mauritius, the UAE, the United Kingdom, the United States, Australia, China, France, Germany, Hong Kong and the Netherlands. Country-specific features with no Indian analogue are given their own sub-paragraphs, among them the UK Statutory Residence Test and the abolition of the non-dom regime, the US Substantial Presence Test, the Chinese six-year rule and the Dutch durable-personal-ties approach
- Chapter 14 — FAQs on Residential Status
- Footnoted to the Income Tax Department’s published non-resident FAQs and extended by the author to the transition. Six questions restate the position under the new Act; the remaining thirteen deal with the repeal, the savings clause, reassessment after 1st April 2026, stays spanning both regimes, and the survival of NRI concessional-regime positions
- Chapter 15 — Case Studies
- Dated fact patterns with full workings. Among them: the employment-purpose exception on a relocation to explore business; four-year and seven-year cumulative counts; deemed residency both established and defeated; firm residence where both partners are non-resident; GAAR and SAAR tested against a relocation to Dubai; a split-year departure followed by a holiday in a third country; BPO income and business controlled from India; short-stay exemption for a US citizen at an Indian branch office; and treaty questions under the India-Germany, India-UK, India-Japan, India-Korea and India-UAE agreements, including the taxing right over a footballer’s signing fee routed through a Korean club.
- Appendix
- Circular No. 346 dated 30-6-1982 (extract); Circular No. 13/2017 dated 11-4-2017 as corrected by Circular No. 17/2017 dated 26-4-2017; Circular No. 789 dated 13-4-2000; Circular No. 6/2012 dated 3-8-2012; Circular No. 157 dated 26-12-1974; the Press Release dated 1-3-2013 on section 90 and the TRC; and the CBDT FAQs on Form 42, opening with a mapping of the old and new form, section and rule references and running to thirteen questions
Each chapter follows one pattern, so the architecture is learned once and used throughout.
- Opening — A chapter panel, then a ‘Background’ paragraph fixing the provision, naming its 1961 counterpart and framing the question
- Numbering — A decimal paragraph system rather than continuous prose: bold upper case at the first level, bold sentence case at the second. All cross-references are to paragraph numbers, never pages
- Running Heads — Three parts, alternating by side. Verso: paragraph number, chapter title, folio. Recto: folio, subject of the governing paragraph, paragraph number
- Statutory Text — Reproduced in italics with the counterpart section bracketed immediately after, and conditions broken out as lettered and roman clauses that preserve the drafting hierarchy
- Illustration — Short Example: blocks on named taxpayers, plus four recurring table types: day-count, year-wise stay, income analysis with a Remarks column, and country snapshot
- Sources — Reproduced material keeps its own numbering; decisions are footnoted at the foot of their own page, numbered 1 to 83 across the book
- Closing Chapters Switch Format — Bold interrogative headings with self-contained answers in the FAQs, and italic facts followed by a fixed Solution sequence in the case studies
| ISBN | 9788167010780 |
|---|---|
| Authors | Sachin Sinha |
| Binding | Hardbound |
| Edition | 2026 |
Related products