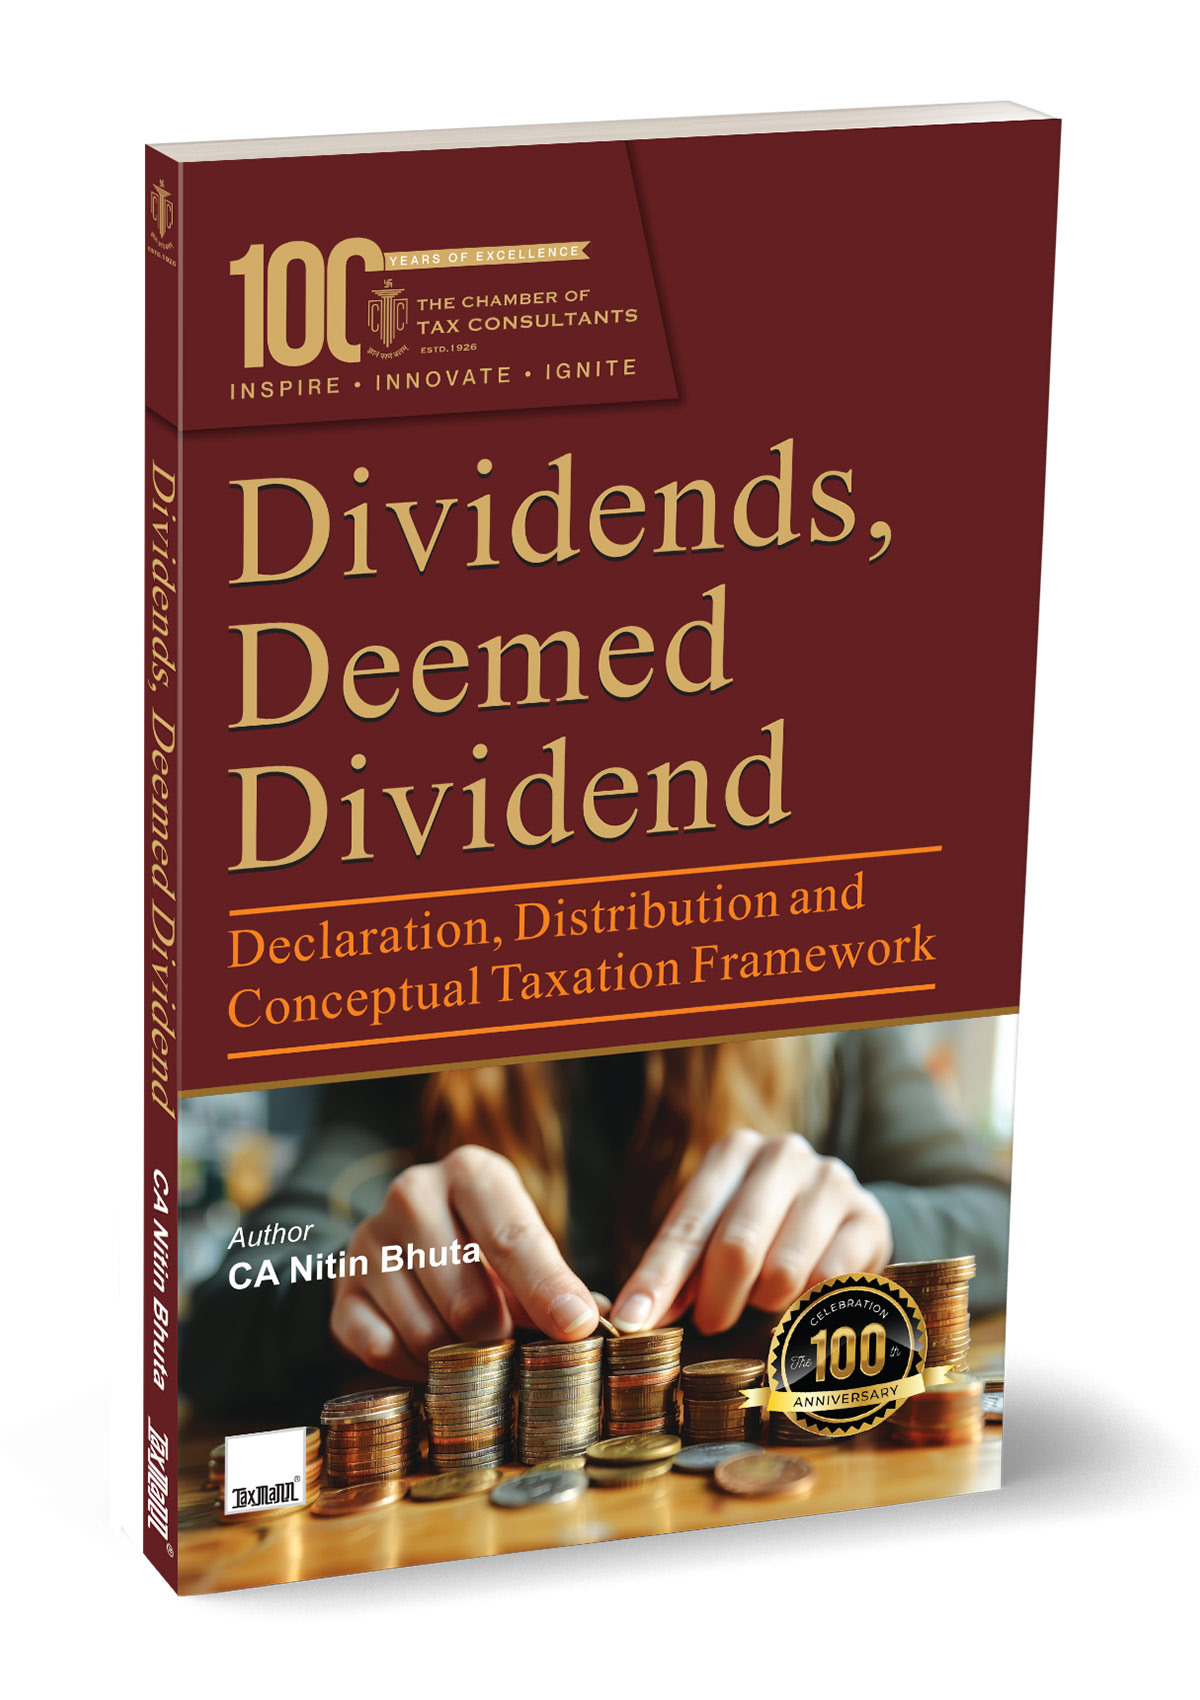
Dividends, Deemed Dividend—Declaration, Distribution and Conceptual Taxation Framework By Nitin Bhuta
Original price was: ₹485.00.₹388.00Current price is: ₹388.00.
A dividend looks like the simplest transaction in corporate finance: a company earns profit, and gives some of it to its owners. That simplicity is an illusion. By the time a single rupee reaches a shareholder, it has had to survive Section 123 of the Companies Act 2013; the inclusive—and famously elastic—definition in Section 2(22) of the Income-tax Act 1961; the newly enacted Section 2(40) of the Income-tax Act 2025; a withholding obligation whose trigger point may have just moved; FEMA’s Non-Debt Instruments Rules; an applicable DTAA read alongside the Multilateral Instrument; and some seventy years of accumulated judicial precedent, much of it decided on facts that no longer exist.
Dividends, Deemed Dividend—Declaration, Distribution and Conceptual Taxation Framework is CA. Nitin Bhuta’s attempt—to hold all of that in a single hand. Drawing on thirty-three years of practice, the author has compressed a subject that ordinarily sprawls across three or four volumes into 142 pages of text across 21 chapters, without hollowing it out. As reviewer CA Srinivasan Anand. G. observes: ‘The subject matter of a lengthy commentary running into 100s of pages in three or four volumes has been captured in a thin handy book in a concise manner.‘
| ISBN | 9789375619956 |
|---|---|
| Authors | Nitin Bhuta |
| Binding | Paperback |
| Edition | 2026 |
Related products